 In 2003, Congress enacted FACTA, the Fair and Accurate Credit Transactions Act. This legislation served as an amendment to the Fair Credit Reporting Act. In addition to allowing consumers to obtain a free yearly credit report from the three nationwide credit companies (Equifax, Experian and TransUnion), the FACTA act also helps to protect individuals from identity theft.
Credit and Debit Card Receipts
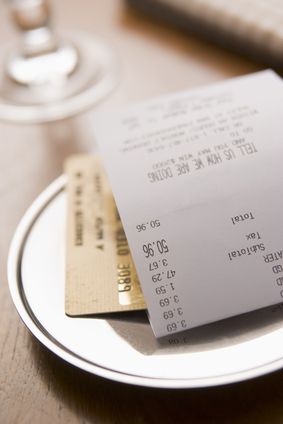
FACTA requires that all businesses truncate consumer credit/debit card account information from a consumer that appears on a printed electronic receipt. This law was gradually phased in over several years and became fully effective in December 2006. Before this time, receipts often included the full debit or credit card account number and expiration date.
The truncation provision forced businesses to allow no more than the last five numbers of the credit or debit card (now appearing on receipts like Account #: **********86145) and does not allow any printing of the card expiration date (Expiration: **/**).
When card information was completely included on credit and debit card receipts, a customer copy of the receipt left behind at a restaurant or tossed in a garbage can could have meant a life-changing experience. Not only was the credit card in question being possibly charged to the max by an identity thief, but additional information could have been received from the initial theft, costing consumers months to years of financial problems and emotional distress.
Business Noncompliance with FACTA
The penalty for businesses who do not truncate information from credit and debit cards on their receipts is quite hefty. This applies across the board to little mom and pop shops to big corporations. The only credit and debit card receipts that are not covered under FACTA are handwritten receipts or those imprinted with card information.
It also does not apply to transaction records a business keeps; it only applies to those credit or debit card receipts given to a customer at the point of sale.
If businesses are found to be non-compliant with the FACTA act, these violations could result in law enforcement actions by the Federal Trade Commission as well as consumer lawsuits. FACTA violations carry fines from $100-$1000 if a business has been found to have willfully failed to comply with FACTA, with additional damages and attorney fees also awarded.
With a consumer class action lawsuit against a company, the amount of fines a business could sustain could be colossal.
Consumers have taken their privacy concerns into their own hands and have filed debit and credit card class action and individual lawsuits against companies who have issued noncompliant printed debit or credit card receipts. These actions have sent a serious warning to the companies who chose not to comply with the legislation, and have helped individuals maintain more privacy over their identity and consumer data information.
FACTA Class Action Lawsuit Information
If you have been issued a credit or debit card receipt that included more than five digits of your card number on the customer copy of your receipt, or if your card expiration date was printed, you may have a legal claim. Lawyers are investigating individual and FACTA class action lawsuits and are able to provide you with a free, confidential discussion of your situation.
Free FACTA Class Action Lawsuit Investigation
If you made one or more purchases and the retailer provided you with a receipt that contained more than the last five digits of your credit or debit card number or the expiration date, you may be eligible for a free class action lawsuit investigation and to pursue compensation for these FACTA violations.
ATTORNEY ADVERTISING
Top Class Actions is a Proud Member of the American Bar Association
LEGAL INFORMATION IS NOT LEGAL ADVICE
Top Class Actions Legal Statement
©2008 – 2026 Top Class Actions® LLC
Various Trademarks held by their respective owners
This website is not intended for viewing or usage by European Union citizens.

FACTA lawsuit investigation: Check your paper receipts for credit card privacy violations
November 6, 2026 | Legal News