 The Fair and Accurate Credit Transaction Act, also commonly referred to as FACTA, was enacted to protect consumers from identity theft or fraud. One of the ways FACTA does this is by setting provisions on what can be displayed on a debit or credit card receipt through a process known as credit card truncation.
FACTA Credit Card Truncation
A debit or credit card receipt that displays a full account number and expiration date are easy targets for identity thieves. According to FACTA rules, a debit or credit card receipt may not include more than the last five digits of the card number.
Additionally, FACTA prohibits the printing of the card’s expiration date on the cardholder’s receipt. However, credit card truncation is not applicable to receipts for that are handwritten or recorded as a card imprint.
Although the law was signed by President George W. Bush on December 4, 2003, different sections have had different effective dates. With regard to credit card truncation requirements, the relevant FACTA provisions came into effect in December 2006 with respect to any cash register or other machine or device that electronically prints receipts for credit card or debit card transactions in use before January 1, 2005.
FACTA compliance was also mandated for one year after December 4, 2003, with respect to any cash register or other machine or device that electronically prints receipts for credit card or debit card transactions that is first put into use on or after January 1, 2005.
Essentially, this means all compliance for FACTA credit card truncation was enforceable in December 2006. Any businesses that have not complied with FACTA rules are subject to heavy fines and open themselves up to possible legal action.
In fact, a common thread among the many FACTA lawsuits is the reference to businesses having had three years to comply with credit card truncation requirements.
Example of Credit Card Truncation
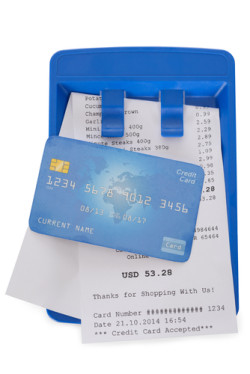
Credit card truncation is important to protect the customer from losing his or her credit card number if he or she loses a receipt. It also protects both the merchant and the customer by not allowing the credit card number to be printed and therefore preventing fraudulent situations. Below is an example of a truncated and non-truncated credit card receipt:
Example 1: Truncated Receipt
Acct# – **** **** **** 9999
Exp ****
Example 2: Non-truncated Receipt
Acct# – 1234 5678 9000 0000
Exp 00/00
If a credit card receipt resembles the second example, or the expiration date is printed on the receipt, then the credit card receipt is a violation of FACTA credit card truncation.
FACTA Lawsuit Information
Many recent lawsuits against businesses that have printed unlawful information on a debit or credit receipt have been successful. Because there is almost strict liability for a FACTA violation, plaintiffs can recover damages of up to $1,000 for each knowing and willful violation of the credit card truncation provision.
Furthermore, under FACTA, class action lawsuits may be brought to enforce credit card truncation rules, in which consumers can pursue massive statutory damages. Statutory provisions also allow for the imposition of punitive damages, and recovery of attorney fees and costs by successful plaintiffs.
Free FACTA Class Action Lawsuit Investigation
If you made one or more purchases and the retailer provided you with a receipt that contained more than the last five digits of your credit or debit card number or the expiration date, you may be eligible for a free class action lawsuit investigation and to pursue compensation for these FACTA violations.
ATTORNEY ADVERTISING
Top Class Actions is a Proud Member of the American Bar Association
LEGAL INFORMATION IS NOT LEGAL ADVICE
Top Class Actions Legal Statement
©2008 – 2026 Top Class Actions® LLC
Various Trademarks held by their respective owners
This website is not intended for viewing or usage by European Union citizens.